
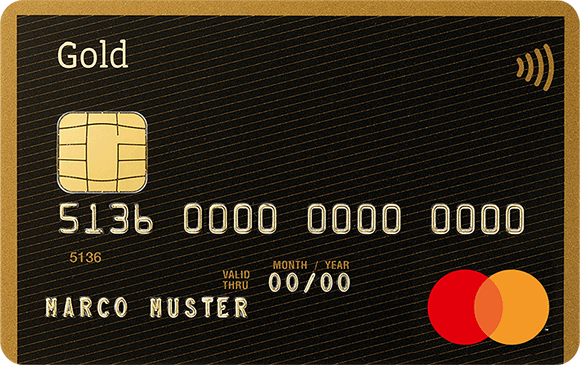

Cembra Mastercard Gold
Cembra
Overall Rating
Annual fee
CHF 135
Network
Mastercard
Rewards Type
No rewards
Our Take on Cembra Mastercard Gold


CHF 135 for a gold card with no rewards and no insurance. Why does this exist?
The Cembra Mastercard Gold is unusual: it's a gold-tier card stripped of the benefits that typically justify gold pricing. No rewards program. No travel insurance. No lounge access. At CHF 135 annually, it serves a narrow audience who specifically wants credit functionality without complexity.
Why Would Anyone Get This?
Let me be direct: most people shouldn't. The CHF 135 buys you a higher spending limit (CHF 5,000-20,000) and the "gold" status, but nothing else. Free cards like Certo One offer cashback. CHF 100 cantonal bank cards include CHF 10,000 trip insurance. What does this card provide? A gold Mastercard that exists.
The intended audience: customers who have rewards fatigue, get travel insurance through work, and want a simple credit card without points, tiers, or redemption catalogs. Some people genuinely prefer this. They're rare.
What Actually Stands Out
The simplicity is the feature. No rewards means no expiring points, no redemption math, no catalog browsing. You use the card, you pay the bill, done. For customers exhausted by optimization culture, this has appeal.
Apple Pay, Google Pay, Samsung Pay, and Garmin Pay all work. The 2% FX fee is average. No income requirement makes it accessible to customers who might not qualify for other gold cards.
What Most Reviews Miss
CHF 135 for essentially no benefits is poor value by any standard metric. You could get free cards with cashback, or pay CHF 100 for cantonal bank cards with insurance. The math doesn't favor this card unless you place negative value on rewards programs (finding them annoying rather than useful).
Cembra Money Bank issues many co-branded cards (IKEA, Certo, TCS, etc.) with better features. This standalone product exists for customers who don't want those partners' branding but want Cembra's credit infrastructure.
The Bottom Line
A stripped-down gold card for a very specific audience who values simplicity over features. Most people should look at free cashback cards or affordable cards with actual benefits instead. Compare alternatives in our best credit cards in Switzerland guide.
Verdict: Only makes sense if you actively dislike rewards programs and have insurance elsewhere. Most people should choose differently.
PROS
- Apple Pay compatible
- Contactless payments for convenient transactions
- Spending limit flexibility ranging from CHF 5000 to CHF 20,000
- Access to multiple digital payment options including Samsung Pay, Apple Pay, and more
- 24-hour customer service support
CONS
- High annual fee (CHF 135)
- High foreign exchange fee (2%)
- No welcome bonus
- No travel insurance
- No medical coverage
- No airport lounge access
Card Details
At a Glance
Annual fee
CHF 135
Rewards rate
-
FX Fee
2%
Fees & Costs
Fees & Costs
First year annual fee
CHF 135
Annual fee (after first year)
CHF 135
Foreign exchange fee
2%
Cash Withdrawal (Domestic)
3.75% (min CHF 10)
Cash Withdrawal (International)
5.75% (min CHF 10)
Late Payment Fee
CHF 30
Rewards Program
Rewards Program
Rewards type
No rewards
Base rewards rate
-
Insurance & Protection
Insurance & Protection
Travel insurance coverage
No travel insurance
Medical insurance coverage
No medical coverage
Purchase protection
No purchase protection
Card Features
Card Features
Card Network
Mastercard
Card Type
Gold
Currency
CHF
Minimum income requirement
No income requirement
Monthly spending limit
CHF 20'000
Airport lounge access
Concierge service
Key Features
- Spending limit flexibility ranging from CHF 5000 to CHF 20,000
- Access to multiple digital payment options including Samsung Pay, Apple Pay, and more
- 24-hour customer service support
- No income requirement
- Contactless payments for convenient transactions
Calculate If This Card Is Worth It for You
= CHF 30'000/year
You Pay
CHF 135
per year
You Get Back
CHF 0
estimated value
Bottom Line
CHF -135
extra cost for perks
Annual calculation:
Move the slider to see how your spending affects the card's value. Miles: 1.5 ct, points: 1 ct.
Rating by Category
Compare to Other Cards
Frequently Asked Questions
- Why does the Cembra Mastercard Gold charge CHF 30 for a late payment?
- CHF 30 sits CHF 7 above the premium-segment average of CHF 23. Cembra and Coop both price late fees on the higher end; cantonal banks settle at CHF 20 for the same lapse. Set up direct debit and forget it; this is one of the avoidable hits across Cembra's lineup.
- Does the Cembra Mastercard Gold actually charge less for domestic ATM withdrawals?
- Yes, 3.75% domestic vs the standard 4.00%, with the CHF 10 floor unchanged. A CHF 500 home pull costs CHF 18.75 here vs CHF 20 elsewhere, so the saving is real but small. Abroad it climbs to 5.75% with the same floor, identical to most premium cards. Use a debit card for cash.
How We Rated This Card
Wondering why Cembra Mastercard Gold got its score? We rate Premium cards using a weighted formula. Here's what counts:
Same formula for every card in this category. No exceptions.
See our full rating methodologyReady to Apply?
Apply for the Cembra Mastercard Gold today and start enjoying its benefits.