
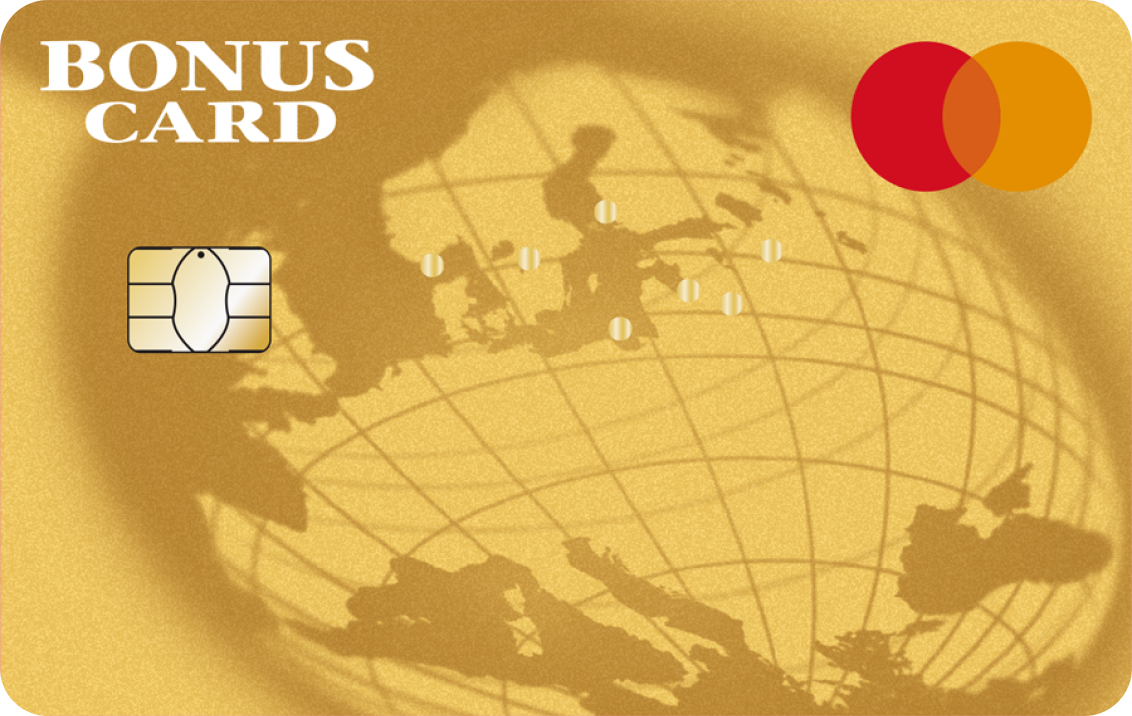

Bonus Card Mastercard Classic
Bonus
Overall Rating
Annual fee
CHF 48
Network
Mastercard
Rewards Type
Points
Also good for
Our Take on Bonus Card Mastercard Classic


Double points on every purchase abroad for CHF 48. Most cards penalize foreign spending. This one rewards it.
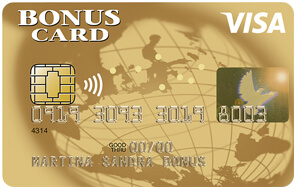
The Bonus Card Mastercard Classic flips the usual Swiss card logic: instead of just charging extra FX fees on international purchases, the MyCountry program doubles your points abroad. At CHF 48 annually, it's a budget-friendly option for shoppers who buy from foreign websites or travel frequently. Bonus Card also offers this on Visa with identical benefits. See also the Bonus Card Visa Classic.
Is CHF 48 Worth It?
It depends on where you spend. MyCountry doubles your Bonus points on all purchases abroad. At partner merchants, you earn up to 5 points per CHF 5; elsewhere, 1 point per CHF 5. Points redeem at 2 points = 1 centime, giving you 0.5-2% effective returns depending on where you shop.
Spend CHF 5,000 abroad annually at double points (10,000 points) and that's roughly CHF 50 in redemptions. The card pays for itself. Add domestic spending at Bonus partners, and returns climb further. For anyone spending in foreign currencies, this is genuinely competitive.
What Actually Stands Out
The MyCountry double points abroad is the headline feature. Most Swiss cards charge 1.75-2.5% FX fees and offer no bonus for international spending. This card charges 2% FX fee (slightly above average) but compensates with doubled rewards. The net effect can be positive for international purchases.
Apple Pay, Google Pay, Samsung Pay, and Garmin Pay all work. Additional cards cost CHF 24 each. At Bonus partner stores, you earn enhanced rates (2, 2.5, or even 5 points per CHF 5), making strategic shopping quite rewarding. Our exchange rates guide compares FX fees across Swiss cards.
What Most Reviews Miss
No travel insurance at the Classic tier. If you want trip cancellation or medical coverage, you need to upgrade to Gold (CHF 144) or Exclusive (CHF 216). This card is purely about rewards and payments, not protection.
The 2% FX fee is slightly above the Swiss average of 1.75%. On CHF 5,000 foreign spending, you'd pay CHF 12.50 extra versus typical cards. The doubled points (worth roughly CHF 50) more than offset this, but don't confuse this with a low-FX-fee card.
The Bottom Line
A budget card that rewards international spending when most Swiss cards penalize it. The MyCountry double points make it genuinely valuable for online shoppers buying from abroad or frequent travelers. Compare alternatives in our best shopping credit cards in Switzerland guide.
Verdict: Worth it if you spend significantly abroad. The doubled points offset the slightly high FX fee.
PROS
- Apple Pay compatible
- Contactless payments for convenient transactions
- 1 welcome bonus points
- Multiple mobile payment options (Samsung Pay, Apple Pay, Google Pay, Garmin Pay)
- 24-hour service for immediate assistance and support.
CONS
- High foreign exchange fee (2%)
- No welcome bonus
- No travel insurance
- No medical coverage
- No airport lounge access
- No concierge service
Card Details
At a Glance
Annual fee
CHF 48
Rewards rate
1 points/CHF
FX Fee
2%
Fees & Costs
Fees & Costs
First year annual fee
CHF 48
Annual fee (after first year)
CHF 48
Foreign exchange fee
2%
Cash Withdrawal (Domestic)
4% (min CHF 10)
Cash Withdrawal (International)
6% (min CHF 10)
Late Payment Fee
CHF 20
Additional Cards
CHF 24/card/year
Rewards Program
Rewards Program
Rewards type
Points
Base rewards rate
1 / CHF
Insurance & Protection
Insurance & Protection
Travel insurance coverage
No travel insurance
Medical insurance coverage
No medical coverage
Purchase protection
No purchase protection
Card Features
Card Features
Card Network
Mastercard
Card Type
Standard
Currency
CHF
Minimum income requirement
No income requirement
Monthly spending limit
CHF 10'000
Airport lounge access
Concierge service
Key Features
- 1 welcome bonus points
- Multiple mobile payment options (Samsung Pay, Apple Pay, Google Pay, Garmin Pay)
- 24-hour service for immediate assistance and support.
- Penchant for cashback: Redeem Bonus points for cash back at 2 points per 1 centime.
- No annual fee
Calculate If This Card Is Worth It for You
= CHF 30'000/year
You Pay
CHF 48
per year
You Get Back
CHF 300
estimated value
Bottom Line
+CHF 252
in your pocket
Annual calculation:
CHF 30'000/yr × 1 points/CHF × 1 ct
Move the slider to see how your spending affects the card's value. Miles: 1.5 ct, points: 1 ct.
Rating by Category
Compare to Other Cards
Frequently Asked Questions
- Should I pick the Bonus Card Mastercard Classic or the Visa version?
- Identical fees, identical points structure, identical insurance. Both charge CHF 24 a year for a partner card, both hit 6% on intl cash withdrawals, both run MyCountry double-points abroad. The only difference is the network logo on the front. Pick whichever isn't already in your wallet.
- How does the Bonus Card Mastercard Classic late fee compare to peers?
- CHF 20, versus CHF 30 at Cembra and Coop. The shopping-segment average sits at CHF 23, so Bonus comes in below average. Set up direct debit and you'll never see this fee, but if you tend to forget due dates, the lower amount adds up to real money over the years.
How We Rated This Card
Wondering why Bonus Card Mastercard Classic got its score? We rate Shopping cards using a weighted formula. Here's what counts:
Same formula for every card in this category. No exceptions.
See our full rating methodologyReady to Apply?
Apply for the Bonus Card Mastercard Classic today and start enjoying its benefits.