
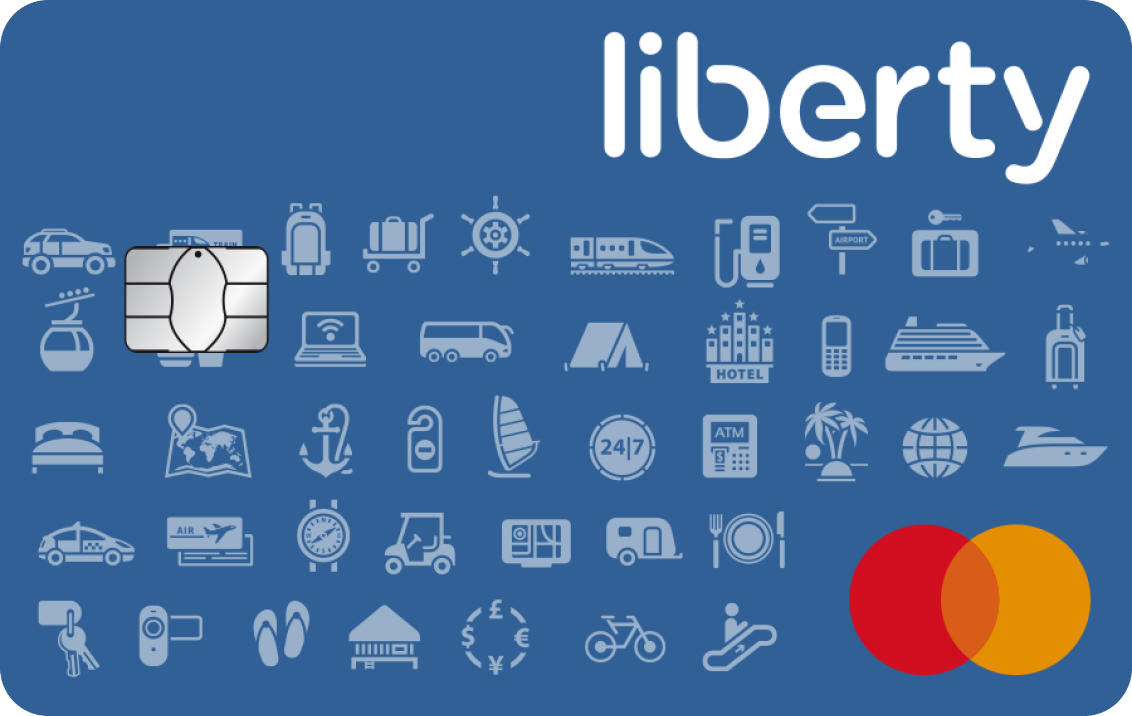

LibertyCard Mastercard
LibertyCard
Overall Rating
Annual fee
CHF 60
Network
Mastercard
Rewards Type
Points
Also good for
Our Take on LibertyCard Mastercard


Double points on every train ticket, fuel stop, and parking meter. For Swiss commuters, this adds up fast.
The LibertyCard Mastercard rewards your daily commute with 2x points on all transportation spending. LibertyCard also issues this on Visa with identical terms. At CHF 60 annually, the card is built for people who spend regularly on transit, gas, parking, and car rentals. If those categories are meaningful in your budget, the focused bonus outperforms generic flat-rate alternatives. See also the LibertyCard Visa.
How the Transportation Bonus Works
Every franc you spend on public transit (SBB/CFF, local buses, trams), gas stations, parking, and car rentals earns 2 Liberty points instead of 1. That is double the base rate, applied automatically. CHF 3,000 in annual transportation spending generates 6,000 points, worth roughly CHF 30-60.
On top of that, MyCountry activates double points on all foreign purchases. Spend CHF 2,000 abroad and collect another 4,000 points. Combine both bonuses and a moderate spender can pull CHF 50-100 in annual return from a CHF 60 card.
What Actually Stands Out
CHF 10,000 trip cancellation insurance is included at no extra cost. That covers most domestic and short-haul European trips. For a CHF 60 card, having any insurance at all is a nice addition.
Apple Pay, Google Pay, Samsung Pay, and Garmin Pay all work. The card handles everyday payments well beyond the transportation niche. Additional cards cost CHF 30 each if you want one for a partner.
What Most Reviews Miss
The 2% FX fee is above average. While MyCountry double points abroad offset some of that cost, the FX rate itself is not competitive. If you spend heavily in foreign currencies, a Cornèrcard (1.2% FX) may save more than LibertyCard's bonus points earn.
Also, the value drops sharply if you don't commute or drive. Work-from-home lifestyles remove most of the transportation bonus. Before committing, tally your actual monthly transit and fuel expenses.
The Bottom Line
A focused card that rewards commuting and travel at an accessible price point. If transportation is a top spending category, the doubled earning genuinely outperforms flat-rate cards. Compare alternatives in our best cashback credit cards in Switzerland guide.
Verdict: Strong choice for daily commuters and frequent drivers. Less compelling if transportation is not a significant part of your budget.
PROS
- Travel insurance coverage up to CHF 10,000
- Apple Pay compatible
- Contactless payments for convenient transactions
- 1 Liberty point per 1 franc spent
- Double points earned on purchases abroad
- Travel insurance coverage of up to 10,000 Swiss francs for trip cancellations.
CONS
- High foreign exchange fee (2%)
- No welcome bonus
- No medical coverage
- No airport lounge access
- No concierge service
Card Details
At a Glance
Annual fee
CHF 60
Rewards rate
1 points/CHF
FX Fee
2%
Travel insurance coverage
CHF 10'000
Fees & Costs
Fees & Costs
First year annual fee
CHF 60
Annual fee (after first year)
CHF 60
Foreign exchange fee
2%
Cash Withdrawal (Domestic)
4% (min CHF 10)
Cash Withdrawal (International)
6% (min CHF 10)
Late Payment Fee
CHF 20
Additional Cards
CHF 30/card/year
Rewards Program
Rewards Program
Rewards type
Points
Base rewards rate
1 / CHF
Insurance & Protection
Insurance & Protection
Travel insurance coverage
CHF 10'000
Medical insurance coverage
No medical coverage
Purchase protection
No purchase protection
Card Features
Card Features
Card Network
Mastercard
Card Type
Standard
Currency
CHF
Minimum income requirement
No income requirement
Monthly spending limit
CHF 10'000
Airport lounge access
Concierge service
Key Features
- 1 Liberty point per 1 franc spent
- Double points earned on purchases abroad
- Travel insurance coverage of up to 10,000 Swiss francs for trip cancellations.
- No annual fee
- Multiple mobile payment options (Samsung Pay, Apple Pay, Google Pay, Garmin Pay)
Calculate If This Card Is Worth It for You
= CHF 30'000/year
You Pay
CHF 60
per year
You Get Back
CHF 350
estimated value
Bottom Line
+CHF 290
in your pocket
Annual calculation:
CHF 30'000/yr × 1 points/CHF × 1 ct
Move the slider to see how your spending affects the card's value. Miles: 1.5 ct, points: 1 ct.
Rating by Category
Compare to Other Cards

Frequently Asked Questions
- Is the LibertyCard Mastercard worth keeping if I rarely drive or commute?
- Probably not. The transport multiplier is the main differentiator, and outside of mobility spend you earn just 1 point per franc (around 0.5% return). If your gas, public transport, and rental spend is under CHF 300 a month, a flat-rate cashback card likely pays more.
- How does MyCountry boost my earnings when I'm abroad?
- Double points on every foreign purchase, layered on top of the base earn rate. So foreign transport earns 4 points per franc (2 base x 2 MyCountry), foreign restaurants and shopping earn 2 points per franc. The boost applies automatically when the merchant bills in foreign currency.
- How much does a partner card cost?
- CHF 30 per year for one supplementary card. That's slightly above the cashback segment average of CHF 22 but lower than most premium cards. Worth it if your partner uses transport-heavy spend that benefits from the 2x bonus and double-abroad points.
How We Rated This Card
Wondering why LibertyCard Mastercard got its score? We rate Cashback cards using a weighted formula. Here's what counts:
Same formula for every card in this category. No exceptions.
See our full rating methodologyReady to Apply?
Apply for the LibertyCard Mastercard today and start enjoying its benefits.