Rating
Luxury credit cards compared: Platinum cards, Black Cards and metal cards in Switzerland
On GetRates, "luxury" means Platinum, metal and Black cards: the platinum credit cards from CHF 400 a year you can apply for, plus invitation-only products like the American Express Centurion. Gold cards live on our best premium credit cards page, because that's where most people's money is better spent. The table above shows every luxury card you can apply for (the Centurion is invitation-only, so we cover it in the Black Card section below): filter by annual fee, foreign currency fee or issuer, open a row for our take, and tick up to three cards to line them up in our comparison tool.
Here's the truth: luxury credit cards are either the best money you'll spend or the dumbest. There's basically no middle ground.
A platinum card costs CHF 400 to CHF 900 every year at its regular price, and the UBS Mastercard Excellence asks CHF 2,000. That's not a typo. You're paying this much for what the banks call "exclusive experiences" (which really means airport lounges, a concierge who books restaurants you could book yourself, and insurance you might never use).
After years of analyzing Swiss financial products, I've seen the pattern. Luxury cards deliver exceptional value for heavy travelers and high spenders. For everyone else, you're literally paying hundreds of francs annually for a metal card that feels nice in your wallet.
The main differences between luxury and premium cards? Unlimited lounge access instead of limited visits, free guests in the lounge, travel status and credits, and beefier insurance packages. Whether that's worth 3x to 4x the annual fee depends entirely on whether you'll actually use this stuff.
October 2026 update: we rebuilt this ranking on 16 October for frequent flyers who actually use the perks. It covers Platinum cards from CHF 400 a year, so the PostFinance Visa Platinum (CHF 250) moved to our premium page and the SWISS Miles & More Platinum joined. The lounge experience, travel status and yearly credits now count alongside insurance, rewards, concierge and net cost, and a higher fee never earns points on its own. That puts the Amex Platinum first: CHF 460 of yearly credits (a SWISS voucher, SIXT ride credit and GaultMillau dining) cut its CHF 900 fee, and it adds Centurion lounges and hotel status with Hilton, Marriott, Radisson and Meliá. On 29 October we checked every fee against the issuers' own pages and added the UBS Mastercard Excellence, which comes second: free Priority Pass for you and a companion, but CHF 2,000 a year plus CHF 1,000 to sign up, so it only pays off if you spend enough for UBS to refund the fee. The UBS Platinum (the same free Priority Pass for you and a companion) follows, then the Cornèrcard Visa Platinum (the best rewards and the lowest foreign currency fee). Ratings are shown on a 2.5 to 5 scale.
How to get a Black Card in Switzerland
Short answer: in Switzerland, the only true Black Card is the American Express Centurion, and you can't apply for it. It's issued by Swisscard (fully owned by American Express since January 2026) and handed out strictly by invitation.
Amex doesn't publish the Centurion's fee, benefits or entry criteria for Switzerland. A Swiss cardholder writing in Inside Paradeplatz in August 2026 reported being charged CHF 4,500 a year, a figure he says Swisscard confirmed by phone. Treat that as a data point, not a price list.
There's no official income threshold either, and income alone won't get you invited. Based on cardholder reports, invitations go to people who already hold an Amex Platinum or Gold, put several hundred thousand francs a year on it for multiple years, and always pay in full. Swisscard looks at your spending history, not your payslip. Our luxury credit card requirements guide goes deeper into what the invitation takes.
Two things people often mix up:
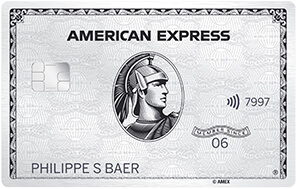
- The Amex Platinum is not the Centurion. The metal Platinum card carries the Centurion head in its design, but it's a separate product you can apply for at CHF 900 a year.
- There's no UBS Black Card in Switzerland. The UBS Visa Infinite you'll find online is a US product from UBS Bank USA. In Switzerland, UBS's top card is the Mastercard Excellence, and you can order it (more on that just below).
Because you can't apply for it, the Centurion isn't in the table above. The table lists the Platinum and metal cards you can actually order.
Is there a UBS Black Card? The UBS Excellence card explained
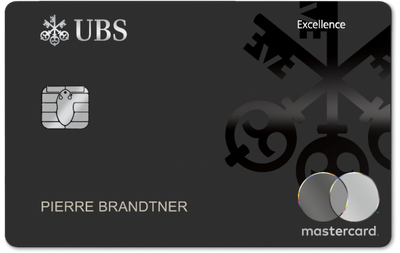
No card from UBS Switzerland is called a Black Card. When people search for the "UBS Black Card", they usually mean the UBS Mastercard Excellence, which UBS itself calls "one of the most exclusive credit cards in the world". Unlike the Centurion, it's not invitation-only: UBS publishes its price and an order link, and its card pages mention no invitation.
Here's what the official UBS price list says:
- CHF 1,000 one-off sign-up fee, then CHF 2,000 a year
- Half the annual fee refunded from CHF 50,000 of yearly spending, all of it from CHF 100,000
- Free Priority Pass lounge access for you and a travelling companion
- A spending limit agreed with you individually
- Foreign currency: the Mastercard rate plus a 1.75% processing surcharge
So what are the UBS Excellence card requirements? UBS doesn't publish an income threshold or eligibility rules. What it does publish is the math: below CHF 50,000 of card spending a year you pay the full CHF 2,000, and only at CHF 100,000 does the card become free (after the CHF 1,000 sign-up fee). If you don't spend at that level, the UBS Platinum gets you the same free Priority Pass for you and a guest for a fraction of the price.
Metal credit cards in Switzerland
Good news if you just want the heavy card: several metal credit cards are open for applications in Switzerland right now.
- American Express Platinum (Swisscard): CHF 900 a year, with one additional metal Platinum card included. Suits frequent travellers who'll use the hotel and lounge perks.
- Cornèrcard Visa Platinum: an 18-gram metal card, CHF 500 a year. New clients applying by 17 January 2027 pay CHF 250 in the first year and get double cashback until 14 March 2027 (details on our Cornèrcard offer page). Suits people who want a metal card with Visa acceptance and cashback.
- Viseca Visa Platinum: metal, CHF 550 a year. Includes free parking at Zurich Airport up to 24 times a year.
What about the UBS Platinum? It's often described as a metal card, but UBS itself only mentions a design inspired by the Gastlosen cliffs, so we leave it off this list.
Here's the honest part: metal is a status feature, not a financial one. It sounds great when it hits the counter, but it doesn't earn you a single extra franc. Pick the card for its fees, FX rate and benefits, and treat the material as a bonus.
Below the Black Card: which platinum credit cards can you actually get?
If you're not on Amex's invitation list (most of us aren't), a platinum card is as high as most people apply. Think of them as the step below Black cards. If lounges and insurance are all you're after, the Gold cards on our best premium credit cards page often get you there for less.
The best platinum card is the one whose lounge rules match how you fly, because annual fees swing from about CHF 400 to CHF 900. Here are the main options with their standard prices:
- UBS Platinum: first 6 months free, then from CHF 34 a month for the card (CHF 43 in the UBS Banking Platinum package). Unlimited free Priority Pass visits for you plus one guest.
- Cornèrcard Visa Platinum: CHF 500 (CHF 250 in year one for new clients until 17 January 2027). Unlimited free Priority Pass for you and a companion, and a foreign currency fee of at most 1.2%, the lowest in this group.
- Viseca Visa Platinum: CHF 550, halved from CHF 40,000 of yearly spending and waived from CHF 80,000. Unlimited Priority Pass entries, sold through many cantonal banks.
- SWISS Miles & More Platinum: CHF 700 for the card duo. The standout is check-in at the SWISS first class counter. Our Miles and More credit card comparison sets it against the Cornèrcard Miles & More Platinum.
- American Express Platinum: CHF 900. Unlimited Priority Pass plus Centurion lounges, hotel status and CHF 460 of yearly credits. It's a metal card.
- UBS Mastercard Excellence: CHF 2,000 a year plus a CHF 1,000 sign-up fee, refunded in part or in full from CHF 50,000 of spending.
Honestly? UBS and Cornèrcard deliver the core Platinum package at roughly half the Amex price.
UBS Platinum: the entry step below Black cards
UBS Platinum is the easiest way in if you already bank with UBS: solid insurance and one of the most generous lounge rules in this group, but nowhere near Centurion territory.
Here's what you get with the UBS Visa Platinum or UBS Mastercard Platinum:
- Price: first 6 months free, then from CHF 34 a month for the card, or CHF 43 a month in the UBS Banking Platinum package
- A 24/7 concierge service
- Priority Pass: unlimited and free for you and one guest, at more than 1,800 lounges (UBS puts the value at around CHF 750 a year)
- Travel Protection Plus insurance, with medical cover abroad up to CHF 1,000,000
- A monthly spending limit of up to CHF 20,000
- KeyClub rewards: 6 points per CHF 1,000 spent
Amex Platinum: the closest you get without an invitation
American Express Platinum is the top card you can apply for in Switzerland's regular Platinum range, and the usual stepping stone to a Centurion invitation. It's also the most expensive of the classic platinum cards (status matters, even if we pretend it doesn't).
What you're paying CHF 900 a year for, according to Amex's own benefit sheet:
- CHF 460 of yearly credits: a CHF 100 SWISS voucher, up to CHF 200 of SIXT ride credit and CHF 40 a quarter at GaultMillau restaurants (on a bill of at least CHF 250)
- Unlimited Priority Pass for you and the included Platinum supplementary card (other guests pay USD 35)
- Centurion Lounges for you plus two guests
- Hotel status: Hilton Honors Gold, Marriott Bonvoy Gold Elite, Radisson Rewards Premium and Meliá Rewards Gold, plus Fine Hotels + Resorts
- Medical cover abroad up to CHF 3,000,000
- 1 Membership Rewards point per CHF 1, a standard welcome offer of 45,000 points (Amex values them at CHF 200) and 10% off at Gübelin, up to CHF 1,500 a year
Use all the credits and the CHF 900 fee drops to a net CHF 440. Skip the SIXT rides and the GaultMillau dinners and you're back near CHF 800. The foreign currency fee is 1.75% on the CHF card.
Visa Platinum: metal without the Amex acceptance issues
You can get Visa Platinum cards from Viseca, Cornèrcard, or your cantonal bank. Visa Infinite is the tier above standard Platinum (because naming schemes in finance are designed to confuse you).
The Viseca Visa Platinum gives you:
- Annual fee: CHF 550, halved from CHF 40,000 of yearly spending and waived from CHF 80,000
- Unlimited Priority Pass (guests pay EUR 30 a visit)
- A 24/7 concierge service
- Medical cover abroad up to CHF 500,000 per event
- 2 surprize points per franc and a foreign currency fee of 1.75%
The nice thing about getting Visa Platinum through your cantonal bank? You keep your local banking relationship while getting national luxury card benefits. Plus, Visa is accepted basically everywhere, unlike Amex which still gets rejected at random Swiss shops.
Platinum card requirements and limits: what do you need?
Short answer: Swiss issuers don't publish a fixed minimum income for a platinum card. Amex, for example, only asks for "a regular income and a positive credit check". No published salary line, no magic number.
In practice, issuers look at three things:
- Your income and fixed costs, to decide whether you can carry the limit
- Your credit record with the ZEK credit bureau and the debt collection register (a clean extract matters more than a big salary)
- Your relationship with the bank: UBS sells its Platinum inside a banking package, and many cantonal banks issue the Viseca Platinum to their own clients
What about the limit? UBS is the only issuer here that publishes one: up to CHF 20,000 a month on the UBS Platinum. The UBS Excellence limit is agreed individually, and the other issuers set your limit after the credit check. For the full checklist, including the Black Card, read our luxury credit card requirements guide.
What do concierge services actually do?
Every luxury card promises a "24/7 concierge". In practice, concierge services handle restaurant reservations, event tickets, travel planning and gift sourcing. Among the platinum cards in our table, the Amex Platinum, UBS Platinum, Cornèrcard Visa Platinum and Viseca Visa Platinum include one.
Here's the honest truth: most cardholders never call their concierge. If you'll actually use it for complex travel planning or hard-to-get reservations, it's genuinely valuable. If you've got Google and 10 minutes of free time, you probably don't need it. Our guide covers credit cards with a concierge service in more detail.
The real cost of luxury cards
The annual fees (brace yourself)
Swiss platinum cards fall into three price buckets:
Entry Platinum
- UBS Platinum (from CHF 34 a month)
- Cornèrcard Visa Platinum (CHF 500)
- TopCard Visa Platinum (CHF 500)
- Viseca Visa Platinum (CHF 550)
Travel heavyweights
- SWISS Miles & More Platinum (CHF 700)
- Cornèrcard Miles & More Platinum package (CHF 750)
- American Express Platinum (CHF 900)
Real money
- UBS Mastercard Excellence (CHF 2,000 plus CHF 1,000 to sign up)
- Amex Centurion (invitation only, fee not published)
The hidden costs nobody talks about
Annual fees are just the start. Here's where luxury cards quietly drain your wallet:
Is unlimited lounge access actually worth it?
Almost every platinum card in our table includes Priority Pass, and most of them with unlimited visits (the SWISS Miles & More Platinum has no lounge access at all). The real difference is guests: UBS Platinum and Cornèrcard let a companion in for free, Amex charges USD 35 per guest (but its Centurion lounges take two guests for free), and Viseca charges EUR 30.
Those guest prices are a fair yardstick for what a visit is worth: roughly CHF 30. Fly ten return trips a year with a lounge on both legs and that's 20 visits, about CHF 600 for you alone and CHF 1,200 if a companion gets in free. UBS values its Priority Pass at around CHF 750 a year. If you fly a few times a year, you're paying for a lounge membership you barely use. Our complete lounge access guide compares the lounge rules of every Swiss card, Gold cards included.
What about the travel insurance everyone forgets they have?
Medical emergency coverage (the important stuff)
Luxury cards include medical insurance abroad, and this is where the cards really differ. Medical cover per card, from our card data and the issuers' benefit sheets:
- Amex Platinum: up to CHF 3,000,000
- Cornèrcard Visa Platinum: up to CHF 1,500,000
- UBS Platinum: up to CHF 1,000,000
- Viseca Visa Platinum: up to CHF 500,000 per event
Amex Platinum tops out at CHF 3,000,000, which is more than most standalone travel insurance policies you'd buy separately. Our credit card insurance guide compares the fine print across every Swiss card so you know exactly what's covered before you need to file a claim.
Trip cancellation and baggage protection
Trip cancellation reimburses you when illness, injury or a family emergency stops you from travelling. Pre-existing conditions and changing your mind are not covered. Baggage cover pays for lost or delayed luggage, but claims usually have tight deadlines, so file them as soon as you land. The limits differ per card, so check the policy before you book.
Rental car insurance (this one actually saves money)
Many luxury cards cover the rental car excess, which means you can skip the rental company's expensive extra insurance. If you rent a car several times a year, that alone can be worth a few hundred francs.
Before you decline rental insurance, read the fine print. Some cards don't cover:
- Certain vehicle types (luxury cars, SUVs, exotic vehicles)
- Specific countries or regions
- Longer rentals
Who should actually get a luxury credit card?
- Flying internationally 8+ times a year. You'll max out lounge access, insurance coverage, and concierge services. At 15+ annual lounge visits, the access value alone covers a good part of the annual fee.
- Spending CHF 75,000+ annually on cards. The rewards add up fast at high volumes. The difference between luxury and premium cards gets bigger as you spend more.
- Too busy to handle your own bookings. If you're a time-constrained professional who'll actually use concierge services for restaurant reservations, event tickets, and travel planning, the time savings are worth real money.
- Traveling 3 to 6 times a year. You get enough lounge access and insurance from Best Premium Credit Cards without the luxury price tag.
- Spending under CHF 50,000 annually. You won't earn enough rewards to offset the premium you're paying for luxury over premium cards.
- Not going to use the extra features. If you won't actively use concierge services or optimize all the benefits, you're just paying for a fancy card that does the same thing as a cheaper one.
How do I actually calculate if luxury is worth it for me?
Here's the simple math you need
Calculate your annual benefit value like this:
Lounge access: How many visits × CHF 30 (roughly what Amex and Viseca charge for a guest) Insurance savings: Number of trips × what a standalone policy would cost you Yearly credits: Only the ones you'd actually use (Amex Platinum: up to CHF 460) Rewards earned: Annual spending × (luxury rate minus premium rate) Concierge value: Hours saved × what your time is worth
Add it all up, subtract the annual fee, and you've got your net benefit. Then compare that to what you'd get from a premium card.
Example: Heavy traveler who flies constantly
Let's say you spend CHF 100,000 yearly and take 12 international trips. These are illustrative assumptions, not a quote:
- Lounge visits (24 × CHF 30): CHF 720
- Insurance replacement (12 × CHF 150): CHF 1,800
- Amex yearly credits, all used: CHF 460
- Extra rewards (CHF 100,000 × 0.5%): CHF 500
- Hotel upgrades (6 × CHF 200): CHF 1,200
- Total value: CHF 4,680
- Amex Platinum fee: - CHF 900
- Net benefit: CHF 3,780
You're coming out close to CHF 3,800 ahead. The luxury card is a no-brainer.
Example: Moderate traveler (most people)
You spend CHF 40,000 yearly and take 4 international trips:
- Lounge visits (6 × CHF 30): CHF 180
- Insurance replacement (4 × CHF 150): CHF 600
- Extra rewards (CHF 40,000 × 0.5%): CHF 200
- Total value: CHF 980
- Luxury card fee: - CHF 500
- Luxury net benefit: CHF 480
- Premium card fee: - CHF 200
- Premium net benefit: CHF 780
See that? You're better off with the premium card. The luxury card is costing you CHF 300 a year for the privilege of having it.
What mistakes do people make with luxury cards?
Metal cards feel great. Platinum branding sounds impressive. But if you're paying CHF 900 annually for a card that delivers CHF 600 in actual value, you're spending CHF 300 a year on prestige. That's an expensive emotional purchase (and trust me, the cashier at Migros doesn't care about your platinum card).
So many people pay luxury card fees and never use concierge services, file insurance claims, or visit airport lounges. Track your actual benefit usage every few months. If you're not capturing value equal to the annual fee, downgrade to Best Credit Cards that match what you actually do.
You can have a luxury card that charges 2% on international purchases. Spend CHF 20,000 abroad and that's CHF 400 in fees. This hidden cost alone can wipe out the value difference between luxury and premium cards. Check the FX fees before you get seduced by the fancy benefits.
Holding several luxury cards with overlapping benefits is just burning money. Multiple Priority Pass memberships, duplicate insurance coverage, what's the point? Consolidate to one primary luxury card and use fee-free alternatives for everything else.
Can foreigners actually get Swiss luxury credit cards?
Yes, if you live here. You'll need a Swiss residence permit, a Swiss address and, in most cases, a Swiss bank account. UBS and Amex Platinum Switzerland both accept foreign residents who qualify.
Here's the catch: your credit history from abroad doesn't transfer to Switzerland. None of it. Issuers judge you on your Swiss record, so new residents often need some months of local banking history before a luxury product gets approved. Our guide to credit cards for expats shows which issuers accept which permits.
My honest take on luxury cards
After analyzing thousands of card setups through GetRates and optimizing my own wallet, here's what I've learned: luxury cards are genuinely valuable for maybe 10% to 15% of Swiss residents. For everyone else, they're expensive vanity.

The math doesn't lie. If you travel internationally 10+ times a year, spend CHF 75,000+ on cards, and actually use the lounges, credits and concierge, a platinum card can return CHF 2,000 to CHF 4,000 a year beyond its fee. That's real money worth capturing. For a deeper dive into requirements, card-by-card breakdowns, and who actually qualifies, check out our complete luxury credit card guide.
But if you travel a few times a year, spend moderately, and just want a card that works everywhere? You're paying CHF 300 to CHF 600 annually for the privilege of having a metal card in your wallet and benefits you'll never touch. Get a solid premium card or even a fee-free Cashback Credit Card instead.
Use the comparison table above. Be honest about your actual travel frequency and spending patterns. The numbers will tell you the truth, even if it's not what you want to hear.
Frequently Asked Questions
What is a Black Card?
"Black Card" is the nickname for the American Express Centurion, a card issued by invitation only. The term is also used loosely for any dark or metal top-tier card. In Switzerland, the Centurion is the only real Black Card: Swisscard issues it, and Amex doesn't publish its fee or entry criteria.
How do I get the American Express Centurion in Switzerland?
You can't apply, you have to be invited. In practice that means holding a Swisscard-issued Amex Platinum or Gold, putting very high spending on it for several years and paying in full every month. There's no published income threshold, and one Swiss cardholder reported a CHF 4,500 annual fee in 2026, so do the math before you accept.
Is there a UBS Black Card, and what is the UBS Excellence card?
There's no UBS Black Card in Switzerland (the UBS Visa Infinite is a US product). The top UBS card here is the UBS Mastercard Excellence: CHF 1,000 to sign up, then CHF 2,000 a year, with half the fee refunded from CHF 50,000 of yearly spending and all of it from CHF 100,000. It includes free Priority Pass for you and a companion, and UBS doesn't require an invitation.
What income do I need for a platinum card in Switzerland?
Swiss issuers don't publish a minimum. Amex asks for a regular income and a positive credit check for its Platinum card; UBS ties its Platinum to a banking package. What matters is a clean record with the ZEK and the debt collection register, plus income that covers the limit you ask for. A strong relationship with your bank helps more than a round salary figure.
What is the limit on a platinum credit card?
It's set individually after the credit check. UBS is the only issuer that publishes a ceiling for its platinum card: up to CHF 20,000 a month. The UBS Mastercard Excellence limit is agreed with you individually. If you need a higher limit for a big purchase, ask the issuer before you travel.
What's the best platinum card in Switzerland?
In our ranking, the Amex Platinum comes first for frequent flyers who use its CHF 460 of yearly credits, Centurion lounges and hotel status. The UBS Mastercard Excellence is second, but only worth its CHF 2,000 fee if you spend CHF 50,000+ a year. For most people, the UBS Platinum and the Cornèrcard Visa Platinum deliver the core platinum card package (unlimited Priority Pass with a free companion, solid insurance) for about half the price. Viseca Visa Platinum suits cantonal bank clients who spend enough to get the fee halved or waived.
Is Amex Platinum actually worth CHF 900 in Switzerland?
Only if you use it heavily. The CHF 460 of yearly credits bring the net cost down to CHF 440, but only if you use the SWISS voucher, the SIXT rides and four GaultMillau dinners a year. Add regular lounge visits and hotel status and it pays off. For occasional travelers, it's a waste of money.