

How to redeem the finpension promo code
- 1
Copy the code
Click the button above. RTEQJB is copied and finpension's sign-up opens in a new tab. It's six capital letters: R, T, E, Q, J, B.
- 2
Register and pick your product
Sign up in the finpension app or web app, choose pillar 3a, vested benefits or Invest, and answer the questions finpension uses to set your strategy. Keep your health insurance card handy: it shows the AHV number you need.
- 3
Enter RTEQJB on the last page
finpension asks for a referral code on the last page of the registration. Paste RTEQJB there. Missed it? You have 24 hours to add it under Profile → Invite friends → Redeem code. After that, the code can no longer be entered.
- 4
Pay in CHF 1,000 within 12 months
As soon as at least CHF 1,000 has reached your finpension portfolio within 12 months, finpension credits the CHF 25 and offsets it against your fees.
Conditions
- Enter RTEQJB when you register or open a new product, at the latest within 24 hours. After that, it can't be added.
- Pay in at least CHF 1,000 within 12 months. The credit only arrives once you have.
- You get a CHF 25 fee credit, not cash: finpension deducts it from the fees you'd otherwise pay. Nothing is paid out.
- Works for pillar 3a, vested benefits and finpension Invest.
- Your fees stay finpension's standard ones (0.39% for the 3a, 0.49% for vested benefits). Using the code costs you nothing extra.
What is finpension?
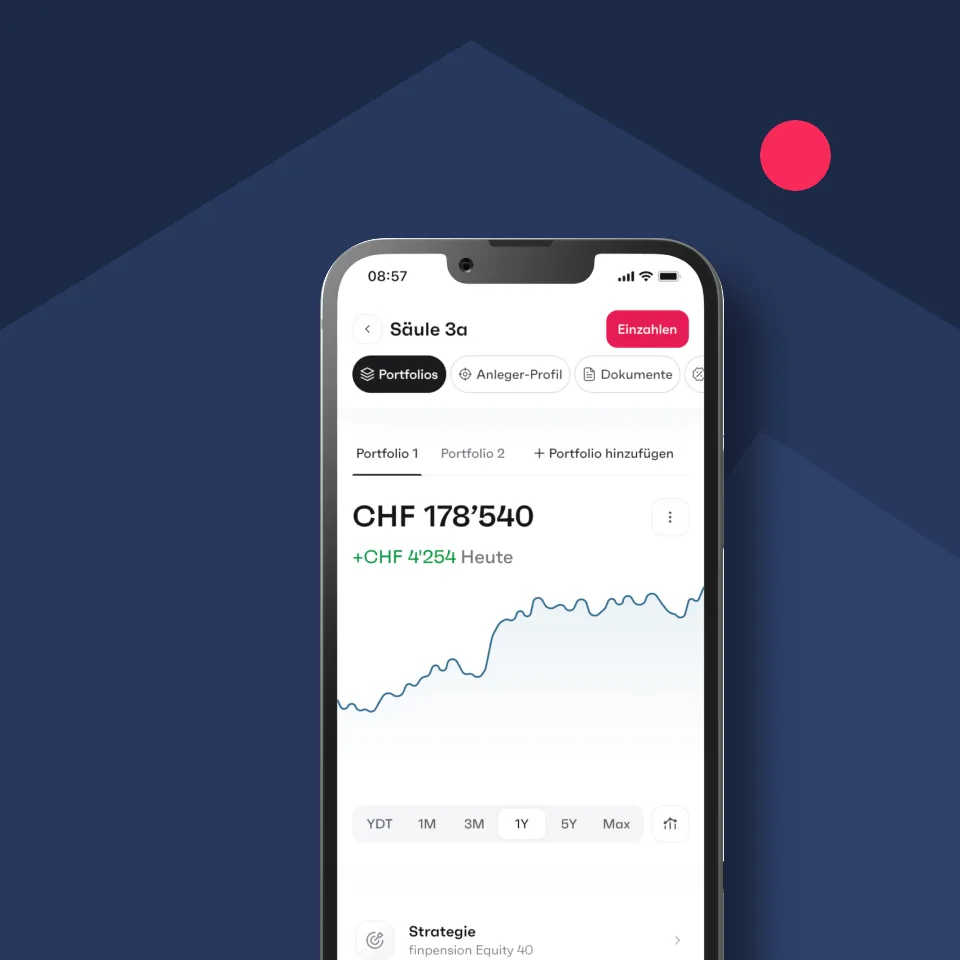
finpension is a pension and investment app from Lucerne, with an office in Geneva. It covers the pillar 3a (as an account or invested), vested benefits (Freizügigkeit), finpension Invest for your free assets, and 1e plans for pension fund money above the usual salary cap. For the invested 3a you choose from 18 ready-made strategies with 0% to 100% in stocks, each in a Global, Switzerland or Sustainable version, or you build your own mix fund by fund. Payments are invested every week, and you can run up to five 3a portfolios side by side.
Your 3a belongs to the finpension 3a Vorsorgestiftung, a pension foundation based in Schwyz and supervised by the Central Swiss BVG and foundation supervisory authority (ZBSA). The strategies use institutional index funds from Swisscanto (Zürcher Kantonalbank) or UBS that are reserved for pension money. That's why there's no fund TER on top of the flat fee, and why these funds can reclaim much of the foreign withholding tax on dividends that ordinary ETFs lose.
Where the offer applies
What does finpension really cost?
One number: 0.39% a year for the pillar 3a, whatever strategy you pick. The index funds carry no TER of their own, and there are no custody, transaction, account or currency-exchange fees on top. Vested benefits cost 0.49% all-in, and finpension Invest 0.39% plus 0.08% to 0.10% in fund costs.
The average invested 3a fund in our comparison costs 0.59% a year, management fee and fund costs combined (90 funds, finpension excluded). A difference of 0.2 percentage points sounds like nothing. Here's what it means if you pay in the maximum every year:
| After | Paid in | finpension | Average 3a fund | You keep |
|---|---|---|---|---|
| 10 years | CHF 72,580 | CHF 88,670 | CHF 87,700 | CHF 970 more |
| 20 years | CHF 145,160 | CHF 215,080 | CHF 210,370 | CHF 4,710 more |
| 30 years | CHF 217,740 | CHF 395,310 | CHF 381,970 | CHF 13,340 more |
Formula: you pay in CHF 7,258 at the start of each year (the 2026 maximum for employees), the portfolio grows 4% a year before fees, and the fee comes off that growth: 3.61% net at finpension, 3.41% for the average fund. Same investment risk in both cases.
The CHF 25 from RTEQJB is a nice extra, but the fee is what makes the difference. On CHF 50,000, finpension charges CHF 195 a year where the average 3a fund costs about CHF 295. Each strategy has its own review: Global 20, Global 40, Global 60, Global 80 and Global 100.
finpension vs VIAC: which is cheaper?
VIAC and finpension are the two apps everyone compares, and we have a code for each. Here's how they stack up on what you'll actually notice:
| finpension | VIAC | |
|---|---|---|
| 3a fee | 0.39% all-in | 0.17% to 0.40% plus 0.01% to 0.06% fund costs |
| Global 100, total cost | 0.39% | 0.41% |
| Global 20, total cost | 0.39% | 0.17% |
| Highest equity share | 99% (Global 100) | 99% (Global 100) |
| Your own strategy | Yes, fund by fund | Yes, within set limits |
| Our code | RTEQJB: CHF 25 fee credit, once | GETRATE: CHF 2,000 fee-free for life |
It depends on your strategy. With a high share of stocks, finpension is a touch cheaper: 0.39% against 0.41% to 0.42% at VIAC. With a cautious strategy, VIAC wins clearly, because its fee drops to 0.17% for Global 20.
On the codes, VIAC's is worth more over time: CHF 2,000 managed fee-free saves up to CHF 8 a year for as long as you stay, while finpension's CHF 25 comes once. Our VIAC promo page explains GETRATE, and the VIAC vs finpension vs frankly comparison goes through fees, strategies and safety in detail.
Vested benefits and Invest: the code works there too
Most code pages only talk about the 3a. But RTEQJB is entered when you open a product, so it also works when you move your vested benefits to finpension after leaving a job, or when you open finpension Invest for your free assets.
Vested benefits cost 0.49% all-in with the same 18 strategies. finpension also lets you split your pension money across two foundations, Freizügigkeit and Freizügigkeit 2, so you can withdraw it in stages later and spread the tax. finpension Invest costs 0.39% plus fund costs of 0.08% to 0.10%. Already a finpension client? You can use RTEQJB when you open one of these products, as long as you enter it within 24 hours.
Is finpension worth it? Our take
Yes, if you want an invested 3a and care about cost. One flat 0.39%, no fund fees on top, institutional funds that recover foreign withholding tax, and full freedom to build your own strategy. With a high share of stocks, it's one of the cheapest ways to invest your 3a in our pillar 3a comparison.
The CHF 25 won't change the maths, so don't choose finpension for the code. Choose it for the fee. If you prefer a cautious strategy, VIAC is cheaper. If you want a bank's name behind your 3a, frankly from ZKB costs 0.44%. To see how every finpension strategy ranks against the other 3a funds, check our best 3a funds ranking.
finpension: frequently asked questions
What is the current finpension code?
It's RTEQJB. Enter it on the last page of your finpension registration, or within 24 hours under Profile → Invite friends → Redeem code. Once you've paid in at least CHF 1,000 within 12 months, finpension credits CHF 25 against your fees.
Is there a finpension referral code?
Yes, RTEQJB works exactly like one. Every finpension client also has a personal referral code in the app. They're all worth the same CHF 25 fee credit to you, so your fees are the same whichever code you use.
Where do I enter the finpension code?
On the last page of the registration, or when you open a new product in the app. If you skipped it, go to Profile → Invite friends → Redeem code within 24 hours.
I forgot to enter the code. Can I add it later?
Only within 24 hours of registering or opening the product, under Profile → Invite friends → Redeem code. After that, finpension no longer accepts the code.
Does the code work for vested benefits and Invest?
Yes. The code covers pillar 3a, vested benefits and finpension Invest. The same rules apply: enter it within 24 hours and pay in at least CHF 1,000 within 12 months.
Can existing finpension clients use it?
finpension accepts a code within 24 hours of opening a new product, so an existing client who opens vested benefits or Invest, for example, can use RTEQJB then. It doesn't apply to products you already have.
finpension or VIAC: which is better?
With a high share of stocks, finpension is slightly cheaper (0.39% against 0.41% to 0.42%). With a cautious strategy, VIAC is, from 0.17%. VIAC's code GETRATE is worth more over time, while finpension gives you more control over the funds.
Is my money safe at finpension?
Yes. Your 3a belongs to the finpension 3a Vorsorgestiftung, not to finpension AG, and the foundation is supervised by the ZBSA. The index funds are special assets held by the custodian bank, so they stay yours even if a bank fails. Pension money held as cash is protected up to CHF 100,000, separately from your own bank deposits.
Does finpension also offer a 3a account?
Yes. You can keep your finpension 3a in cash instead of a strategy. Interest follows the Swiss National Bank policy rate, currently 0.00%, and the same 0.39% fee applies, so the net return is about -0.39% a year. That makes sense for parking money briefly before you switch to a strategy, which you can do at any time. For cash you plan to keep, a 3a savings account pays more.
Does GetRates earn money from finpension?
Yes. finpension pays us a one-off commission when someone opens an account with RTEQJB. It costs you nothing, your fees stay the same, and it has no influence on our rankings.
About the author
Entrepreneur who bootstrapped a SaaS to multi-million revenue. Building GetRates.ch to bring transparency to Swiss finance.
About the reviewer
Works in Swiss banking, with a background in anti-money-laundering investigations and cross-border payments. Checks GetRates.ch content for accuracy and hidden conditions before it is published.


