
How to redeem the findependent promo code
- 1
Copy the code
Click the button above. GETRATES3A is copied and findependent's 3a page opens in a new tab. Enter GETRATES3A when the app asks for a code.
- 2
Download the app and register
findependent is app-only, so get it on iOS or Android and start your registration there. Opening a 3a works 24/7 and you only need CHF 1 to start.
- 3
Enter GETRATES3A at registration
findependent asks for the code during your initial registration in the app. Enter GETRATES3A there. Don't skip this step: the code counts for new clients at sign-up, and only one code is accepted per client.
- 4
Choose a solution and make a first payment
Pick one of the 15 ready-made strategies or build your own, then pay in by QR bill from any Swiss bank. CHF 1 is enough: once your first 3a deposit is booked, findependent manages CHF 2,000 of your 3a assets without its fee.
Conditions
- For new findependent clients only, one code per client.
- Enter GETRATES3A during your initial registration in the findependent app. If you forgot, contact findependent support right away and mention the code. We can't promise they'll add it afterwards.
- The code counts once your first 3a deposit is booked. CHF 1 is enough.
- You get a fee-free allowance, not cash: findependent simply skips its 0.29% fee on CHF 2,000 of your 3a assets. Nothing is paid out.
- There's no time limit. Once applied, the allowance stays for as long as you're a client, and your fee on everything above CHF 2,000 stays the standard 0.29%.
What is findependent?
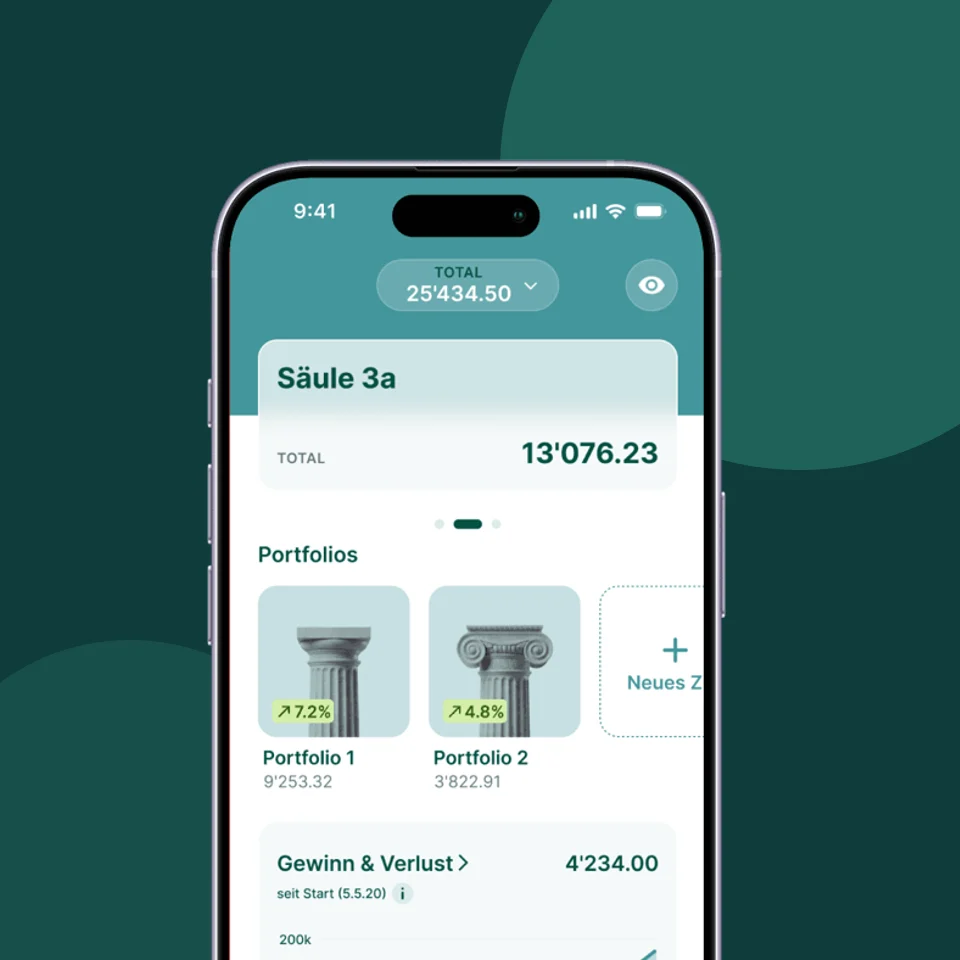
findependent is the investing app of Findependent AG, a FINMA-supervised securities firm based in Aarau. Its investing app has been around since 2021, and the pillar 3a went live on 19 October 2026. You choose from 15 strategies: three focuses (Standard, Global and Switzerland) at five risk levels from 20% to 99% in stocks. Or you build your own portfolio from 33 Swisscanto index funds. You can start with CHF 1 and run up to five separate 3a portfolios, which helps you stagger withdrawals at retirement and cut the tax.
Your 3a belongs to the findependent 3a Vorsorgestiftung, a pension foundation legally separate from Findependent AG. If the company failed, your 3a wouldn't be affected. The index fund units are held at Zürcher Kantonalbank (ZKB) as special assets, outside any bankruptcy estate. About 1% sits as cash at Hypothekarbank Lenzburg, protected up to CHF 100,000 by the bankruptcy privilege. The funds are institutional Swisscanto index funds with a 0.00% TER, and for US and Japanese equities findependent uses pension-only IPF funds that are exempt from foreign withholding tax.
Where the offer applies
- findependent Global 99Pillar 3aRead our review
- findependent Global 80Pillar 3aRead our review
- findependent Global 60Pillar 3aRead our review
- findependent Global 40Pillar 3aRead our review
- findependent Global 20Pillar 3aRead our review
- findependent Standard 99Pillar 3aRead our review
- findependent Standard 80Pillar 3aRead our review
- findependent Standard 60Pillar 3aRead our review
- findependent Standard 40Pillar 3aRead our review
- findependent Standard 20Pillar 3aRead our review
- findependent Switzerland 99Pillar 3aRead our review
- findependent Switzerland 80Pillar 3aRead our review
- findependent Switzerland 60Pillar 3aRead our review
- findependent Switzerland 40Pillar 3aRead our review
- findependent Switzerland 20Pillar 3aRead our review
What is CHF 2,000 fee-free worth in francs?
Let's be honest about the size. findependent charges one fee, 0.29% a year, whatever strategy you pick. The code waives it on CHF 2,000 of your 3a assets, so the saving is the same for everyone:
| Period | Fee saved |
|---|---|
| Per year | CHF 5.80 |
| 10 years | CHF 58 |
| 30 years | CHF 174 |
Formula: CHF 2,000 × 0.29% × years. The allowance is a fixed CHF 2,000, so the saving doesn't grow with your balance.
Where it shows is early on. With CHF 10,000 in your findependent 3a, the code brings your effective fee down from 0.29% to 0.232%. Nice, but the 0.29% itself is what saves you real money over the years.
findependent 3a review: what we found
We scored all 15 findependent 3a strategies with the same rubric as every other 3a fund in our database. All five Global strategies make our top 31 of 109, led by Global 99 at #1. The Standard and Switzerland focuses exist too, at the same five risk levels, and rank between #3 and #37: you'll find all 15 in the list of strategies on this page.
Keep two things in mind. These ranks rest on findependent's back-test, because the 3a only launched on 19 October 2026: the 0.29% fee is real, the returns are simulated. And the older findependent reviews you'll find online cover the investing app, not the 3a, so they won't tell you much about it.
What does findependent cost?
One number: 0.29% a year, all-in. It covers management, custody at ZKB, rebalancing, strategy changes, deposits and incoming transfers. It's charged quarterly on your average balance, per portfolio, so running several portfolios costs nothing extra. The funds carry no TER of their own, there are no currency-exchange markups because every fund trades in CHF, and there's no stamp duty or exchange fee.
That's the lowest total cost of any 3a fund in our database at 40% equities and above. On CHF 50,000, findependent charges CHF 145 a year, against CHF 195 at finpension and about CHF 205 for VIAC Global 100. Two things to know: the Swiss real estate fund in the 20, 40, 60 and 80 strategies invests in other real estate funds that carry their own costs, and findependent hasn't published its fee for early withdrawals (home ownership, self-employment, emigration). Transferring out to another 3a provider is free. Each strategy has its own review: Global 20, Global 40, Global 60, Global 80 and Global 99. To see what your own 3a payments could grow to, try our 3a calculator.
Ranked #1 in our 3a comparison, but on a back-test
findependent Global 99 comes out #1 of 109 in our 3a fund ranking, just ahead of VIAC Global 100. Before you get excited, here's the catch: the findependent 3a only launched on 19 October 2026, so there's no real track record yet. The returns findependent publishes are a back-test built from index data after all costs, from January 2005 to September 2026. On that basis, Global 99 shows +180.6% cumulative over 10 years, with a worst calendar year of -42.9% in 2008.
So the ranking leans on two things: a fee we can verify today, and simulated returns we can't. The fee part is solid. The performance part tells you how the strategy would have behaved, not how it did. findependent will show live performance from October 2026, and the ranking will reflect real figures as they come in.
findependent vs VIAC vs finpension
VIAC and finpension are the two apps findependent has to beat, and we have a code for each. Here's how the three compare on what you'll actually notice:
| findependent | VIAC | finpension | |
|---|---|---|---|
| 3a fee | 0.29% all-in | 0.17% to 0.40% plus 0.01% to 0.06% fund costs | 0.39% all-in |
| Top equity strategy, total cost | Global 99: 0.29% | Global 100: 0.41% | Global 100: 0.39% |
| Top strategy's rank (of 109) | #1 (back-tested) | #2 | #7 |
| Our code | GETRATES3A: CHF 2,000 fee-free, no time limit | GETRATE: CHF 2,000 fee-free for life | RTEQJB: CHF 25 fee credit, once |
On fees, findependent wins at every equity level from 40% up. Only VIAC Global 20 is cheaper, at 0.22% in total for a cautious strategy. The codes from findependent and VIAC work the same way (CHF 2,000 managed for free), while finpension's CHF 25 comes once.
Where VIAC and finpension still have the edge: years of real performance, and finpension also offers a 3a cash account. Our VIAC promo page and finpension promo page explain their codes, and the VIAC vs finpension vs frankly comparison covers the two incumbents in detail.
Is findependent worth it? Our take
If cost is what you care about most, yes. 0.29% all-in is the lowest fee we've seen for an invested 3a at 40% equities and up, the funds are institutional Swisscanto index funds held at ZKB, and you can start with CHF 1. The code won't change your life, but it's a free, permanent discount for typing ten characters.
Where I'd hesitate: the 3a is brand new, so its returns are a back-test, not a track record. Money is invested only once a week, there's no 3a cash account, it's app-only with no advisor, and the early-withdrawal fee isn't published yet. If a long track record matters to you, VIAC or finpension are the safe picks. To see how every strategy ranks, check our pillar 3a comparison and our best 3a funds ranking.
findependent: frequently asked questions
What is the current findependent code?
It's GETRATES3A. Enter it during your initial registration in the findependent app and findependent won't charge its fee on CHF 2,000 of your 3a assets, with no time limit.
Where do I enter the findependent code?
In the findependent app, during your initial registration. findependent is app-only (iOS and Android), so there's no web sign-up where you could enter it instead.
findependent code for 3a or for investing: which one should I use?
It depends on what you're opening. The findependent codes you'll find around the web, like findependent's own GO20, give a CHF 20 start credit on the findependent investing app. GETRATES3A is the 3a code: CHF 2,000 managed fee-free, with no time limit. findependent accepts only one code per client, so you have to pick. If the 3a is what you're opening, GETRATES3A is worth CHF 5.80 a year, so it overtakes a one-off CHF 20 after about 3.5 years. If you mainly want the investing app, a CHF 20 start-credit code pays more up front. findependent hasn't said whether GETRATES3A also unlocks the CHF 20 on the investing side.
I forgot to enter the code. Can I add it later?
The code is meant for your initial registration. If you forgot, contact findependent support straight away and mention GETRATES3A, but we can't guarantee they'll add it later.
Can existing findependent clients use it?
Possibly, but it isn't confirmed. The code is entered at your first registration, and findependent accepts only one code per client. findependent hasn't confirmed whether people who already use the findependent investing app can apply GETRATES3A when they add a 3a. If that's you, ask findependent support before you open the 3a.
How much is the findependent code worth?
CHF 5.80 a year, because findependent's fee is 0.29% on everything. That's CHF 58 over 10 years and CHF 174 over 30. On a CHF 10,000 balance, your effective fee drops from 0.29% to 0.232%.
Is findependent's performance real?
Not yet. The findependent 3a launched on 19 October 2026, so the returns it shows are a back-test: index data from January 2005 to September 2026, after all costs. That's how findependent Global 99 ranks #1 of 109 in our comparison. Treat it as a simulation, not an achieved return. Live performance follows from October 2026.
Is my money safe at findependent?
Yes. Your 3a belongs to the findependent 3a Vorsorgestiftung, a pension foundation legally separate from Findependent AG, which is itself supervised by FINMA. Fund units are held at ZKB as special assets that stay yours even if a bank failed, and the roughly 1% in cash at Hypothekarbank Lenzburg is protected up to CHF 100,000 by the bankruptcy privilege.
findependent, VIAC or finpension: which is better?
On cost, findependent: 0.29% all-in against finpension's 0.39% and up to 0.41% at VIAC Global 100. VIAC is only cheaper with a cautious Global 20 strategy. VIAC and finpension have years of real performance, while findependent's figures are still a back-test. VIAC's GETRATE code gives you the same CHF 2,000 fee-free as GETRATES3A.
Does findependent offer a 3a account?
No. The findependent 3a is investments only, there's no 3a cash or savings account. If you want to keep your 3a in cash, a 3a savings account is the way to go.
Does GetRates earn money from findependent?
Yes. findependent pays us a one-off CHF 25 each time someone signs up with GETRATES3A. findependent also paid a one-off integration fee to be listed faster; it has no effect on the ranking. Neither costs you anything, your fee stays the same, and findependent is scored with the same rubric as every other 3a fund.
About the author
Entrepreneur who bootstrapped a SaaS to multi-million revenue. Building GetRates.ch to bring transparency to Swiss finance.
About the reviewer
Works in Swiss banking, with a background in anti-money-laundering investigations and cross-border payments. Checks GetRates.ch content for accuracy and hidden conditions before it is published.